 Lodge preferences are saved.
Remortgaging to Buy a Holiday Lodge: The Equity Trap Buyers Should Understand
Your home might be worth considerably more than you paid for it.
If you’ve built up equity over the years, it can be tempting to use some of that money to buy a holiday lodge of your own.
Remortgaging could make that possible.
By replacing your existing mortgage with a larger one, you might be able to release money towards the purchase of a lodge without having to save the entire amount separately.
But, there’s a catch.
Having equity in your home doesn’t necessarily mean you can afford to buy a lodge, and the money you release isn’t free.
You’re borrowing against the property you live in to pay for a holiday home that could lose value over time.
If you’re wondering, “can I remortgage to buy a lodge home?”, the answer is potentially yes.
The more important question is whether using your home as security is the right way to fund it.
Can You Remortgage Your House to Buy a Lodge?
Yes, you might be able to remortgage your main home to raise money towards buying a holiday lodge.
This is usually known as capital raising or additional borrowing.
To put it simply, your lender replaces your existing mortgage with a larger loan, or agrees to additional borrowing under an arrangement with your current lender.
Once the remortgage completes, you can use the released funds towards your lodge purchase.
For example, imagine your home is worth £300,000 and you have £150,000 left to repay on your mortgage.
You have £150,000 in equity before taking account of any costs associated with selling or borrowing.
That doesn’t mean you can automatically borrow another £150,000.
Your lender will consider your income, outgoings, credit history, the amount you already owe and the maximum loan it is willing to offer against your property.
If the lender approves a larger mortgage, you could use some of the additional funds to buy a lodge outright or contribute towards its purchase price.
However, remortgaging isn’t guaranteed.
Your lender must agree to the borrowing, and the resulting repayments need to be affordable.
The Catch: You’re Borrowing Against Your Main Home
This is the part buyers should think about most carefully.
A lodge can provide years of holidays, family memories and somewhere to escape your usual routine.
But, those benefits don’t change the nature of the borrowing used to pay for it.
If you increase the mortgage on your main home, you are taking on more debt secured against the property you live in.
If you can’t keep up the repayments, your home could be at risk.
Your Monthly Repayments Could Increase
If you increase your mortgage balance, your monthly repayments will generally rise, unless other changes to the mortgage offset the effect.
You might also find that your new mortgage has a different interest rate or term.
If you switch lenders or leave an existing deal early, fees and early repayment charges could apply.
Ask for a comparison of your current mortgage costs and the proposed new arrangement.
Look at the total amount repayable over the term, not just whether the new monthly payment fits your budget today.
You Could Be Paying For the Lodge Long After Its Best Years
A traditional house is a different type of asset from a lodge on a holiday park.
Many holiday lodges are sold with an agreement allowing the owner to keep the unit on a particular pitch, rather than ownership of the land beneath it.
Depending on the park and agreement, the right to keep the lodge there may be limited by a licence or pitch agreement.
Lodges can also depreciate, and resale values depend on factors such as age, condition, demand and the terms of the park.
This creates a potential mismatch – you could be repaying a mortgage secured against your main home for many years, while the lodge itself loses value or becomes more expensive to maintain.
That doesn’t mean buying a lodge is a bad decision.
It means you should view it primarily as a lifestyle purchase, rather than assuming it will grow in value to cover the borrowing.
Your Circumstances Could Change
A remortgage is a long-term financial commitment.
Your income, household expenses and priorities may change, even if buying a lodge feels comfortably affordable now.
Before proceeding, consider whether you could still manage the repayments if your income fell, your household costs increased or you needed to fund an unexpected repair at home.
You should also leave enough financial breathing room for the lodge’s ongoing expenses.
Using all your available borrowing capacity to fund the purchase could leave little room for unexpected costs.
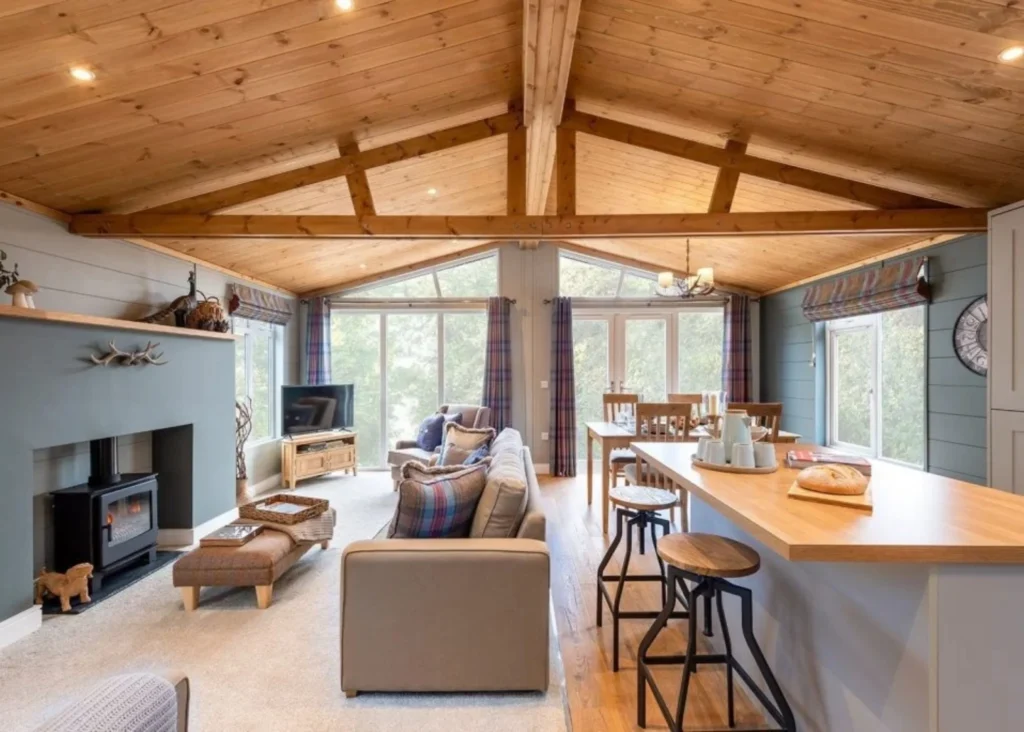
Don’t Forget the Cost of Owning the Lodge
The advertised price is only the beginning.
Before deciding how much to borrow, work out the full cost of keeping the lodge.
Depending on the park and the ownership agreement, you might need to budget for:
- Annual Site Fees – Payments for keeping the lodge on its pitch. Check what they include and how they can increase.
- Utilities – Electricity, water, gas or other services, depending on the property and park.
- Insurance and Maintenance – Cover for the lodge, repairs, upkeep and replacement of worn furnishings or equipment.
- Decking and Extras – Some lodges include decking and other features, while others may require additional spending.
- Park Restrictions – Seasonal opening dates, occupancy rules and limits on subletting can affect how you use the property.
- Future Resale Costs – Ask whether the park charges commission or administration fees if you sell, and whether any conditions apply to the sale.
These costs matter because the mortgage payment is only one part of your ongoing commitment.
Imagine you can afford the increased mortgage payment, but haven’t accounted for annual site fees, maintenance and insurance.
The purchase might appear manageable at first, but become much more expensive once everything is included.
A realistic budget should cover both the borrowing and the cost of actually owning the lodge.
Can You Get a Mortgage on the Lodge Instead?
This is where the type of lodge you want to buy becomes important.
Many holiday lodges on UK holiday parks can’t be financed with a conventional residential mortgage.
They’re often treated differently from bricks-and-mortar homes because the buyer owns the lodge itself, but does not own the land on which it stands.
Some specialist finance options might be available, depending on the lodge, the park and the lender.
However, you shouldn’t assume that every lodge qualifies for a mortgage.
Remortgaging your main home is one possible way to raise the money, but it isn’t the only option.
Depending on your circumstances, alternatives could include:
- Using Savings – You avoid taking on additional debt, although you should retain enough savings for emergencies.
- Buying a Less Expensive or Pre-Owned Lodge – This may reduce the amount you need to borrow. Check the unit’s condition, age, pitch agreement and remaining permitted lifespan or licence term.
- Specialist Lodge Finance – Compare the interest rate, fees, repayment period and total cost carefully.
- Waiting and Saving – Delaying the purchase may give you time to build a larger deposit and reduce the amount you need to borrow.
The Verdict: Can You Remortgage to Buy a Lodge Home?
Yes, it might be possible to remortgage your home to release equity towards a lodge purchase.
Whether you can do so depends on your lender’s criteria, your financial circumstances and the amount you can afford to repay.
The important thing is to look beyond the equity figure.
You’re increasing the borrowing secured against your main home to fund a holiday property that comes with its own running costs and may depreciate.
If the figures work and you understand the risks, remortgaging could help you achieve your goal of owning a lodge.
If it would leave you financially stretched, consider a less expensive property, another finance option or waiting until you have more savings.
A lodge should give you somewhere to relax, not leave you worrying about whether you can afford to keep it.